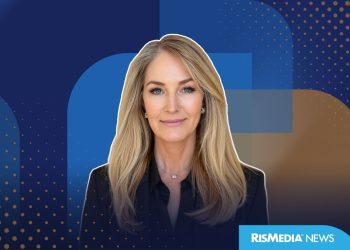
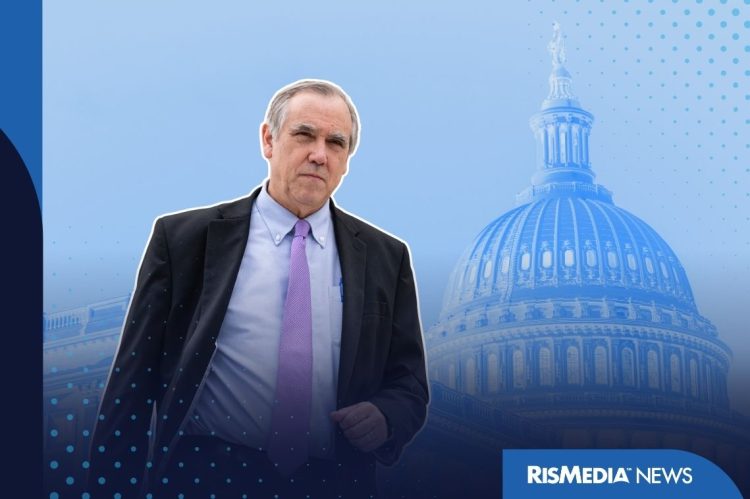
Above, U.S. Senator Jeff Merkley
As interest rates rise and homeownership becomes increasingly out of reach for many, policymakers continue to search for ways to address the affordability crisis.
In the latest legislative action to try and address housing affordability, U.S. Senator Jeff Merkley (D-OR) and cosponsor Sen. Ron Wyden (D-OR) introduced an initiative that could provide federal support for prospective homebuyers.
The Homeownership Promise Act—which was referred to the Senate Committee on Banking, Housing, and Urban Affairs on Sept. 23—would ensure the Department of Housing and Urban Development (HUD) establishes savings accounts titled “Homeownership Promise Accounts.” In these accounts, HUD would match every $1 contributed by the homebuyer with $5.
“Working families should be able to afford a decent home in a decent community,” Merkley stated in the press release. “For millions of young Americans, homeownership remains further out of reach than ever before, keeping them from establishing the foundation that has enabled middle-class families to build equity for generations.”
The proposal stipulates that the accounts will not exceed $60,000, and the account cannot consist of more than $10,000 made by personal contributions by eligible families.
That, according to Merkley, would create a “credible path” for aspiring homebuyers to buy a “modest home” by the time they turn 30 years old.
These Promise Accounts would be available for settlement at the closing for a purchase of an eligible home with an eligible family. The bill outlines that eligible families must mean one or two first-time homebuyers who are not less than 18 years old. The first-time homebuyers must also have never owned a principal residence and have completed a housing counseling program approved by HUD.
The bill defines an “eligible home” as a, “principal residence acquired by an eligible family at a purchase price, not including closing costs, that does not exceed the median single-family purchase price for the area as determined by the (HUD Secretary) with such adjustments for differences in structure, and for new and old housing as the Secretary determines to be appropriate.”
Legislative continuation
The proposal by Merkley is just the latest in a long series of bills aiming to encourage homeownership.
Merkley’s current bill would directly contribute to homebuyers’ purchasing power, rather than seek long-term solutions to regulatory or supply and demand challenges, like the recently passed omnibus bill. His proposal shares some similarities to another bill that was recently presented.
Also predating the Oregon senators’ proposal, U.S. Representative Haley Stevens (D-MI) introduced the Homeownership Savings Act on May 7, which was endorsed by the Mortgage Bankers Association. The act would “amend the Internal Revenue Code of 1986 (IRC) to allow the establishment of homeownership savings accounts (HOSAs),” according to the original bill.
Generally, the revised IRC would allow the HOSAs to be tax-free and have a lifetime contribution limit of $40,000.
“For too many Michiganders, the American Dream of owning a home is slipping away,” Stevens said in the press release. “Families are working hard just to keep up with everyday costs while homeownership moves further out of reach. This bill is about making sure the next generation of Michiganders can afford to live in the communities they call home.”
Housing affordability was on the political docket even prior to Merkley and Stevens’ proposed bills. During the 2024 presidential election cycle, former Vice President Kamala Harris announced her intentions to financially assist homebuyers. Her campaign included a potential proposal to provide $25,000 in down payment support and $10,000 mortgage assistance for first-time homebuyers.
Currently, both bills have been referred to different committees. The Committee on Banking, Housing, and Urban Affairs will review and possibly alter Merkley’s proposal, while the Committee on Ways and Means is reviewing Stevens’ bill.
Bridging the homeownership gap
In his press release, Merkley points out that the age of first-time homebuyers is at an all-time high of 40 years old, with the share of buyers dropping to just 21%.
The age of first-time homebuyers is likely attributed to how long it takes to afford a home and its down payment. A Rocket report released earlier this summer found that buyers in Midwestern cities could afford a down payment after saving for about four years. Their coastal counterparts however, may not have the funds for a down payment until several decades later.
Coupled with the unaffordability of down payments and homes, it’s no surprise that consumers are not optimistic about the lagging economy. The index by the University of Michigan reports that consumer sentiment is at its lowest reading in four months, and is down 15% from January 2026.
Other groups are looking for different solutions for housing issues. The ‘Let America Build’ initiative—founding participants include Realtor.com®, Zillow, RISMedia and more—is a public awareness campaign aiming to spread housing shortage awareness and push lawmakers to address the issue. The campaign specifically endorses the construction of more homes, recently the campaign showcased a mobile activation in the streets of Boston.
It’s too early to indicate where Merkley’s housing down payment savings initiative will go, but it represents one of many attempts by lawmakers to address the ongoing housing crisis.
“My new Homeownership Promise Act would restore the promise of homeownership—one of the foundations that working families need to thrive—by allowing all Americans to save for a home and live that piece of the American Dream,” Merkley concluded in the press release.